
Mean Reversion Trading: Rules, Indicators and a 33-Year SPY Test


Contents
- Mean reversion trading in 30 seconds
- What is mean reversion?
- The math behind it, for advanced readers
- How does mean reversion trading work?
- When does mean reversion work best?
- Mean reversion vs. trend following
- Five indicators for mean reversion
- Our test: two RSI rules on SPY since 1993
- A chart-based alternative: the 1-2-3 reversal
- Pairs trading: mean reversion between two markets
- What does the research say?
- Pros and cons of mean reversion trading
- Who is mean reversion for?
- Conclusion: is mean reversion the right strategy for you?
- Frequently asked questions about mean reversion trading
- About the author
Hardly any price moves in a straight line. After a strong move up or down, most markets are pulled back toward their average. That observation is the core of mean reversion trading: you buy when others sell in panic and sell when euphoria has pushed the price too far. It is one of the few approaches that deliberately trades against the current move.
This guide shows how the principle works, which indicators make the distance from the average visible and what two common rule sets did on SPY over 33 years. We ran the test ourselves, with the rules fixed before we looked at the results. The numbers are less flattering than many blog backtests, and that is the point: mean reversion delivers high hit rates, but hit rates alone do not make a strategy. This article follows our editorial policy.
Mean reversion trading in 30 seconds
- Definition: mean reversion is the tendency of prices to move back toward their long-term average after a strong deviation.
- The logic: you buy oversold markets and sell overbought ones, against the current move, expecting the correction.
- Key tools: Bollinger Bands and Keltner Channels mark extreme zones, the RSI measures the overextension, and the z-score makes it comparable across markets.
- Our test: two RSI rules on SPY won 78 to 80 percent of their trades from 1993 to 2026, but returned 1.7 and 5.1 percent a year against 10.4 percent for buy and hold.
- The risk: in strong trends the average moves away, and the expected correction does not come.
What is mean reversion?
Mean reversion is the statistical tendency of a price to move back toward its historical average after a strong deviation. Traders use it to bet on corrections after overreactions. Extreme moves correct in most market phases, and that observation is the base of the approach.
An example makes it concrete. A stock has traded around $50 for months. If it jumps to $80 without anything changing at the company, the chance of a pullback toward the average rises. The price is not wrong because a formula says so, but because there are fewer buyers willing to keep adding at that level.
The idea comes from statistics. In the 1880s, Sir Francis Galton described it in his work on body height: children of very tall parents were, on average, closer to the average than their parents. Traders apply the same principle to market overreactions.
The logic is simple. Markets overshoot: euphoria pushes prices too high, panic pushes them too low, and neither extreme lasts long. As a trader, you look for markets whose price is far from its average and take a position against the current move. Our guide to range trading shows the same idea inside a sideways market.
The market phase decides. Mean reversion works best in sideways markets. Strong trends keep shifting the average up or down, so a stock in an uptrend keeps setting new, higher averages. That is where the classic logic fails, and it fails systematically, not only now and then.
The return also does not come on schedule. Sometimes it takes days, sometimes weeks, and if you enter too early you sit through the move or get stopped out. A short-term example with fixed rules is the Turtle Soup method, which trades failed 20-day breakouts.
The math behind it, for advanced readers
Mean reversion can be measured, which makes the search for setups systematic instead of subjective. The average is usually a moving average: a 20-day simple average adds the last 20 closes and divides by 20, and every current price is compared with that reference.
To compare deviations across markets, quantitative traders use the z-score. The z-score says how many standard deviations a price is away from its average. A value above 2 or below minus 2 counts as an extreme deviation. Its advantage is that a z-score of 2 means the same in gold as in EUR/USD, even though their price levels are completely different.
How fast a price returns is described by the half-life. In the Ornstein-Uhlenbeck model, a speed parameter called theta measures how strongly price is pulled back; in this continuous-time model with a positive theta, the half-life, the natural logarithm of 2 divided by theta, is the time in which the expected deviation shrinks by half. It is a property of the model and the data it was estimated on, not a promise about any single move; estimated on daily data, it says little about intraday behavior.
Whether a series tends to return at all can be tested. The Augmented Dickey-Fuller test checks, under its statistical assumptions, whether the null hypothesis of a unit root can be rejected, which would point to a stationary series that fluctuates around a stable average. A rejection does not mean that trading the series is profitable. For everyday trading, the basic sequence is enough: calculate the average, measure the deviation, trade the extremes.
How does mean reversion trading work?
A mean reversion trade follows four steps that build on each other. You define the average, measure the deviation, enter at an extreme and exit near the mean.
- Define the average: a simple or exponential moving average gives the reference line, for example the 20-day average.
- Measure the deviation: Bollinger Bands draw two standard deviations around the average; the RSI measures the move on a scale of 0 to 100.
- Enter at an extreme: far below the average, the market counts as oversold, and the chance of an upward correction rises; above it, the reverse applies.
- Exit near the mean: conservative traders close at the average; aggressive versions wait for the full countermove and accept more risk.
Many typical mistakes come from entering during a running trend. Three conditions make it more likely that the approach can work at all:
- Stationarity: the market must fluctuate around a stable average. In trends, the average keeps moving, and a “cheap” price often gets cheaper.
- Liquidity: enough volume and tight spreads matter, because costs in thin markets eat the small profit before the trade works.
- Sideways phases: in a range, the average stays stable and outliers correct more reliably.
When does mean reversion work best?
The time frame changes the hit rate noticeably. Intraday charts from 5 minutes to 1 hour give several setups a day, especially in forex and futures, at the price of constant watching. Daily charts filter more noise; positions typically run three to ten days, which suits a full-time job.
Weekly charts give the fewest but calmest signals. Holding periods run from several weeks to months. As a rule of thumb, the time frame should fit how fast the deviation you trade tends to shrink. A half-life estimated on daily data describes daily swings; whether the same market reverts on a 5-minute chart has to be checked on intraday data.
Not every market suits the approach equally. Major currency pairs such as EUR/USD often move sideways, because high liquidity and opposing fundamental forces limit the swings. Commodities such as oil or gold also show reversion tendencies, above all in phases without a clear macro driver.
In stocks, selection decides. Large, liquid stocks are cheaper to trade than small caps, because spreads are tighter, and defensive sectors often swing more steadily than volatile tech names. Large indices such as the S&P 500 rise over the long run, so their price is not a stationary series; what traders use there are short-term pullbacks inside the trend, which is exactly what our test below does.
Mean reversion vs. trend following
Mean reversion and trend following are opposite philosophies. One bets on reversal, the other on continuation. Mean reversion buys weakness and sells strength; trend following buys strength because trends tend to continue.
The risk profiles differ just as much. Mean reversion produces many small wins with a high hit rate, and now and then a large loss when the correction does not come. Trend following produces many small losses and a few large winners, and the two feel very different to trade.
The practical answer is often both. Nobody knows in advance which market phase comes next, so many experienced traders combine the two approaches; our guide to momentum trading covers the trend side. Toby Crabel’s fund is one disclosed example: as of June 2022, its program statistics split the style into 55 percent momentum, 21 percent counter trend and 13 percent trend following, according to our portrait of Toby Crabel.
The ADX helps to classify the phase. Readings below 25 suggest a sideways market, readings above it a trend. The ADX lags the move, though, so market structure remains the more important signal.
Five indicators for mean reversion
The right indicators separate a rule-based approach from guessing. These five are the most widely used, and each one draws a line or a scale around the average. Our overview of trading strategies shows where mean reversion fits among other approaches.
- Moving averages: the simple average weights all prices equally; the exponential average weights recent prices more and reacts faster. An average alone gives no threshold for an extreme.
- Bollinger Bands: a 20-day simple average with bands two standard deviations above and below it. A touch of the outer band shows a stretched market, but in strong trends price can ride the band for days.
- RSI: the Relative Strength Index measures recent gains against losses on a scale of 0 to 100; readings above 70 count as overbought, below 30 as oversold. Shorter settings such as RSI(2) or RSI(4) give more signals.
- Williams %R: developed by Larry Williams, it shows where the close sits in the recent range on a scale of 0 to minus 100, the same quantity as the stochastic oscillator turned upside down. Readings above minus 20 count as overbought, below minus 80 as oversold.
- Keltner Channels: bands a multiple of the Average True Range above and below an exponential average. They run smoother than Bollinger Bands and react less to single outliers.
For intraday traders, the VWAP is a common reference line. It weights the average by volume, and many day traders treat it as the session’s mean; our VWAP guide shows how it is calculated.
Our test: two RSI rules on SPY since 1993
Many published mean reversion backtests show hit rates of 80 percent or more, often from a few dozen trades. We wanted to see what two common rule sets did over a long period, so we tested them ourselves on SPY, the S&P 500 ETF. The rules follow the short-term RSI pullback strategies popularized by Larry Connors; we fixed the exact thresholds before looking at any result.
| Rule | Entry | Exit |
|---|---|---|
| A | Close above the 200-day average and RSI(10) below 30; buy at the next open | Next open after RSI(10) rises above 40, or after 10 trading days |
| B | Close above the 200-day average and RSI(4) below 25; buy at the next open | Next open after RSI(4) rises above 55 |
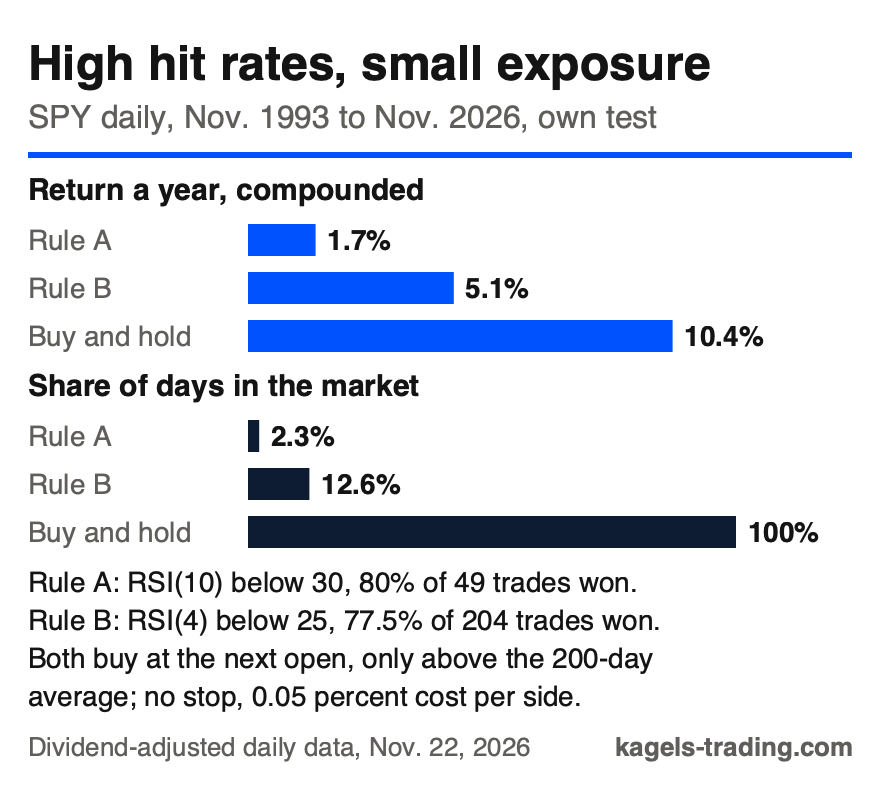
Daily SPY data from Yahoo Finance, dividend-adjusted, signals from November 12, 1993 (the 200-day average is first available on November 11) to November 20, 2026. RSI with Wilder smoothing. Long only, no stop, each trade reinvests the full capital, idle cash earns nothing, and a fixed 0.05 percent cost per side stands in for commissions and spread; there is no separate slippage model. Own calculation.
 Click to enlarge
Source: Kagels Trading, own backtest.
Both rules won most of their trades. Rule A won 80 percent of 49 trades, about one and a half signals a year; Rule B won 77.5 percent of 204 trades. The average trade made 1.14 and 0.82 percent. On those numbers, both look like the high hit rates that make mean reversion popular.
The total return tells a different story. Rule A compounded to 1.7 percent a year and Rule B to 5.1 percent, against 10.4 percent a year for simply holding SPY. The main reason is exposure: the rules were in the market on only 2.3 and 12.6 percent of all days, and in our calculation the cash between trades earned nothing. Per day invested, they did well; as a whole strategy, they left most of the market’s return on the table.
The losses also show the typical profile. In Rule B, the average win was 1.54 percent, but the average loss 1.64 percent, and the worst trade, from July 28 to August 16, 2011, lost 8.6 percent. With no stop, a single correction that keeps going can cost several winners.
Read these numbers as a sample, not a promise. They come from one market that rose strongly over the period, with rules that only buy above the 200-day average. In a sideways or falling market, the picture would look different. Our guide to backtesting explains why a small number of trades and a single market say little about the future.
A chart-based alternative: the 1-2-3 reversal
Not every mean reversion approach needs an indicator. The 1-2-3 pattern, which Victor Sperandeo described in his book “Trader Vic: Methods of a Wall Street Master”, defines a trend reversal by three points on the chart.
- Point 1: the last extreme of the trend, the lowest low in a downtrend.
- Point 2: the first countermove that breaks the trendline.
- Point 3: the failed attempt to continue the old trend; the closer it is to point 1, the stronger the signal.
- Entry and stop: enter on the break of point 2, with the stop just beyond point 3.
Unlike the two RSI rules, this pattern comes with a price-based stop. The stop defines the intended exit and the planned risk of each trade, which suits traders who do not want an open-ended risk; gaps and slippage can still make the actual loss larger.
Pairs trading: mean reversion between two markets
Pairs trading is a mean reversion strategy that trades the price gap between two closely related securities instead of a single price. Two stocks from the same industry move largely in parallel for years. If one suddenly runs ahead while the other lags, the gap widens beyond its usual range. You buy the laggard and sell the leader short; if the gap closes, the pair makes a net profit, even if one of the two positions loses.
The aim is to reduce market exposure. One position is long and one is short, but that alone does not remove the market risk; how neutral the pair really is depends on the position sizes and the hedge ratio between the two. A high correlation also does not prove that the spread is stationary. The gap is usually measured with the z-score of the spread: above 2 signals an unusually wide gap, and the position is closed as it moves back toward 0. The statistical groundwork is larger than with any other approach here.
The main risk is a broken relationship. After a takeover or a profit warning, the historical link can break for good, and the spread keeps widening while both sides lose. A stop on the spread is therefore a must, even though many single-market mean reversion rules do without a stop; our guide to the stop loss order covers the order types.
What does the research say?
The academic base is older than most trading blogs. In 1988, James Poterba and Lawrence Summers reported in “Mean reversion in stock prices”, published in the Journal of Financial Economics, evidence that stock returns are negatively autocorrelated over longer horizons: strong phases tended to be followed by weaker ones. They also noted that a random walk could not be rejected at conventional significance levels, so the evidence is suggestive rather than conclusive.
In the same year, Eugene Fama and Kenneth French reported a similar structure. In “Permanent and Temporary Components of Stock Prices” in the Journal of Political Economy, they split prices into a permanent and a temporary component; only the temporary part reverts to the mean. Both studies work with returns over several years, not with the short-term swings that most traders trade.
The evidence is mixed, and the execution decides. Profitability depends on three points: the right market, disciplined execution and consistent position sizing. With a hit rate of 70 percent and losses larger than wins, a handful of big losses can ruin a year, so position size matters more than the entry signal.
Pros and cons of mean reversion trading
Mean reversion has clear strengths and structural weaknesses. You should know both before you put real money on the line, because the weaknesses show up rarely but hard.
Pros of mean reversion
- High hit rate: most trades end in profit, which makes the approach easier to stick with.
- Clear rules: entries and exits can be expressed in numbers, which reduces gut decisions.
- Easy to automate: the rule-based logic fits backtests and trading systems.
- Research base: two independent 1988 studies found mean reversion in stock prices.
Cons of mean reversion
- Small wins per trade: losses are often larger than wins, so single losses weigh heavily.
- Fails in trends: in directional markets, losses pile up because the average moves along.
- Stops are awkward: tight stops cut off the countermove, wide stops raise the maximum loss.
- Low exposure: in our test, the rules were rarely in the market and lagged buy and hold.
Who is mean reversion for?
Mean reversion suits traders who already follow trends. The two approaches earn in different market phases, which can stabilize the overall result. It works best for swing and position traders on daily and weekly charts; very short-term traders pay far more in costs.
It does not suit everyone. If you cannot buy into a falling market without panicking, you will break the rules when it counts. And if you trade without a fixed risk limit, the first real trend phase can cause serious damage; keep every trade in a trading journal so you see that early.
Conclusion: is mean reversion the right strategy for you?
Mean reversion works, but not everywhere and not all the time. The effect is documented in research, and in our test both rules won four out of five trades. At the same time, both earned far less than simply holding the market, because they were rarely invested.
Bjarne’s advice from systematic trading: treat mean reversion as one part of a system, not the whole system. Pick one rule, test it on your market with enough trades, and check the exposure and the size of the losses, not only the hit rate. Start small, document every trade and increase risk only after several months of measured results.
Frequently asked questions about mean reversion trading
What does mean reversion mean?
Mean reversion means that prices tend to move back toward their average after an extreme move. If a stock rises from $50 to $80 without any fundamental change, the chance of a correction toward its historical average rises.
Which indicators are best for mean reversion?
The most common are Bollinger Bands, the RSI, Williams %R, Keltner Channels and moving averages. They mark how far price has moved from its average. Quantitative traders also use the z-score to compare deviations across markets.
Does mean reversion trading work?
It can, in the right market phase. In our test on SPY from 1993 to 2026, two RSI rules won 78 to 80 percent of their trades, but returned 1.7 and 5.1 percent a year against 10.4 percent for buy and hold, because they were rarely in the market.
What is the difference between mean reversion and trend following?
Mean reversion bets on a reversal; trend following bets on continuation. Mean reversion has a high hit rate with small wins and occasional large losses; trend following has many small losses and a few large winners.
What time frame is best for mean reversion?
It depends on how fast the market returns to its average. Daily charts with holding periods of three to ten days suit most traders. The time frame should fit how fast the deviation you trade tends to shrink, which you can estimate as a half-life on data of that time frame, the time in which the expected deviation halves.
Is pairs trading a form of mean reversion?
Yes. Pairs trading bets that the price gap between two related securities returns to its usual range. It aims to reduce market exposure, but its neutrality depends on position sizes, and it carries the risk that the relationship between the two breaks for good.
This English edition is based on our German edition on kagels-trading.de and has been adapted for international readers.
More Chart Techniques guides
- Draw key levels
Support and Resistance: How to Draw and Use Key Levels
Where useful levels come from, how to draw zones with a stated rule and how to turn a level into a trade plan.
- Read price action
Price Action Trading: How to Read Charts Without Indicators
Market structure, key zones and three bar patterns, with a core setup and a real SPY example where the signal failed.
- Read candlestick charts
How to Read Candlestick Charts: Body, Wicks and Context
Open, high, low and close in one candle, body and wicks, two real Gold candles read step by step and how often patterns really occur.
- Smooth candles with Heikin Ashi
Heikin Ashi Candles: Formula, Signals and What the Smoothing Costs
The Heikin Ashi formula, how to read colors and wicks, a year of SPY data with a third fewer color changes, and why orders belong on the real chart.
- Know candlestick patterns
Candlestick Patterns: 10 to Know, Tested on Real Data
Ten patterns with rules and a cheat sheet, counted on DAX, S&P 500, EUR/USD and Gold since 2014: most are rare, none is a signal on its own.
- Trade the hammer candle
Hammer Candlestick: Spot It, Trade It, Know Its Limits
Three features, the difference to inverted hammer and hanging man, entry and stop, and how rarely the hammer appeared in four markets since 2014.
- Spot a morning star
Morning Star Candlestick: Rules, Real Cases, Limits
Three measurable rules, every morning and evening star in four markets since 2014, and two real cases: one reached its target, one hit its stop.
- Spot a topping tail
Topping Tail Candlestick: Rules, Silver Example and Limits
Six measurable rules for the bearish rejection candle, a silver candle from January 2026 checked step by step, the difference from the shooting star and how to trade it with a stop.
- Combine timeframes
Multi-Timeframe Analysis: A Weekly and Daily Workflow
How to combine the weekly chart for context and the daily chart for entry under one stated rule, with a documented SPY case from June 2025.
- Trade pullbacks
Pullback Trading: Entries, Stops and Failed Setups
Pullback or reversal, limit against confirmation entry, and one fixed rule set on three real QQQ cases: a target, a stop and a cancelled setup.
- Trade sideways ranges
Range Trading: Boundaries, Orders and Two Documented Fades
A 14-session rule to draw horizontal boundaries, three order-type variants and two Alpaca-verified SPY fades, one that reached the target and one that was stopped out.
- Read a consolidation
Consolidation in Trading: What the Range Tells You
What a consolidation is, why 25 years of index data showed no stable direction edge from narrow ranges or the prior trend, and two DAX breakouts from 2026.
- Read chart formations
Chart Patterns: Reversals, Continuations and Failures
Reversal, continuation and bilateral formations with the measured-move convention per pattern and two documented SPY rectangle cases.
- Trade rising and falling wedges
Rising and Falling Wedge Patterns: How to Trade Them
How to spot both wedges, where to set entry, stop and target, and why Bulkowski ranks the rising wedge with a downward breakout last of 36 patterns.
- Trade triangle breakouts
Triangle Pattern: Ascending, Descending and Symmetrical
Ascending, descending and symmetrical triangles: entry, stop and target, three chart examples and what Bulkowski's data say about reliability.
- Trade the cup and handle
Cup and Handle Pattern: Rules, Targets and Real Hit Rates
Rounded cup, short handle: entry, stop and target, why volume matters, and Bulkowski's numbers, 61 percent reach the target but 47 percent fall back after the breakout.
- Trade breakouts
Breakout Trading Strategy: Entries and False Breakouts
How often breakouts fell back into the range in our count of 1,472, and how to plan entry, stop and position size.
- Draw and trade trendlines
Trendline Trading: How to Draw Trendlines and Trade Them
How to draw trendlines with a fixed rule, four strategies for bounces, breaks and retests, and a real SPY line break without a lasting reversal.
- Draw a pitchfork channel
Andrews Pitchfork: How to Draw It, Trade It and Test It
Three pivots, a median line and two parallels, Schiff variants, a trade plan and how often price reached the median line in 746 cases.
- Use Fibonacci levels
Fibonacci Retracement Levels: How to Draw and Trade Them
How to calculate and draw retracement levels, trade pullbacks with confluence and a stop at the structure, and what a ten-year test says about the levels.
- Set Fibonacci targets
Fibonacci Extension: Levels, How to Draw It and Calculator
Three-point extension targets from the end of a pullback, why they differ from levels beyond 100%, a free calculator and three SPY swings, one without a single target reached.
- Trade gaps
Gap Trading Strategy: How to Trade Gaps and When Gaps Fill
Opening and full gaps, the four classic gap types, how often SPY gaps filled in our count since 2001, and plans for gap fill and gap and go.
- Calculate pivot points
Pivot Points: Formulas, Types and How to Trade Them
Formulas for standard, Fibonacci, Woodie, Camarilla and DeMark pivots, a free calculator, which session counts and a real SPY day.
- Swing trade
Swing Trading: 4 Strategies, Risk and Real Examples
Four swing trading strategies on the daily chart, position size, gap risk and US rules, with two hypothetical SPY pullbacks: one hit its target, one was stopped out.
- Choose a trading strategy
Trading Strategies: 7 Approaches and How to Pick the One That Fits
Seven strategies compared by market phase and holding period, with setups, weak spots and BaFin data on why more trading meant more losers.
- Identify market stages
Stage Analysis: Stan Weinstein's Four Market Stages
Stan Weinstein's four stages on the weekly chart, a Stage 2 checklist and two TSMC breakouts: one ran for a year, one gapped through its stop.
- Trade momentum
Momentum Trading: How It Works, What the Data Shows and Where It Fails
Momentum from candles to stock rankings, what the US momentum factor made since 1927, its 2009 crash, a three-step rule set and exits.
- Choose a chart type and timeframe
Trading Charts: Types, Timeframes and How to Read Them
Line, bar, candlestick and Heikin Ashi charts, charts without a time axis and the right timeframe for each trading style, with current EUR/USD, gold and DAX examples.
- Read Kagi charts
Kagi Charts: Reversal Amount, Shoulders and Signals
One line, one reversal amount, thick yang and thin yin: tested on DAX hourly data and compared with Renko and point and figure.
- Screen for growth leaders
CAN SLIM: William O’Neil’s Seven Rules for Growth Stocks
William O'Neil's seven CAN SLIM criteria with thresholds, his selling rules, a free screen with real counts and what the tests really show.
- Read Wyckoff ranges
Wyckoff Method: Accumulation, Distribution and Springs
Accumulation and distribution with phases A to E, springs and upthrusts as optional tests, and two real TSMC ranges read with and without hindsight.
- Trade Darvas boxes
Darvas Box Strategy: Rules, Entries and Stop Losses
The box rules step by step, when the edges become known, where the stop goes, and a mechanical test on TSMC in 2024 with two honest results.
- Count Elliott waves
Elliott Wave Theory: Rules, Patterns and Fibonacci
The five-wave pattern, three hard rules, zigzags, flats and triangles, Fibonacci ratios and a real DAX count, from the first German translator of the standard work.
- Understand Smart Money Concepts
Smart Money Concepts (SMC): What They Are and What Holds Up
The seven SMC building blocks, BOS vs CHoCH vs MSS, one labeled SPY sequence that held, one that failed, and what a chart can and cannot show.
- Understand ICT trading
ICT Trading: Silver Bullet, Killzones and What Holds Up
Michael Huddleston's Inner Circle Trader method: Silver Bullet, Judas Swing, the 2022 model and killzones in New York time, with one SPY setup that worked and one that failed.
- Trade order blocks
Order Blocks: How to Spot, Draw and Trade the Zone
The three conditions behind a valid order block, entry and stop at the zone, two SPY cases from 2026 and a 25-year count where a fixed rule lost money.
- Trade fair value gaps
Fair Value Gap (FVG): How to Spot, Trade and Test It
The three-candle rule, bullish, bearish and inverse FVG, two SPY cases from 2026 and a 25-year count of how often gaps were revisited and traded.
- Trade inverse fair value gaps
Inverse Fair Value Gap (IFVG): Rules, Examples and a Test
When a broken gap counts as inverted, three entry styles, one SPY retest that held, one that failed, and a 25-year test with trend and sweep filters.
- Trade failed breakouts with Turtle Soup
Turtle Soup Trading: Raschke Rules, ICT Version and a Test
Linda Raschke's original rules, Turtle Soup Plus One and the ICT version side by side, two SPY examples and a 25-year test on SPY and QQQ.
- Read a break of structure
Break of Structure (BOS): Rules, CHoCH vs MSS and a Test
Which swing counts, BOS vs CHoCH vs MSS under one stated convention, two SPY breaks that won and lost, and a 25-year test against ordinary days.
- Read a change of character
Change of Character (CHoCH): Rules, BOS vs MSS and Data
The first close against the trend, close versus wick, CHoCH vs BOS vs MSS, two SPY cases and what the trend did next after 287 CHoCHs on SPY and QQQ.
- Read a market structure shift
Market Structure Shift (MSS): Rules, BOS vs CHoCH and Data
MSS as a CHoCH with a sweep and a fair value gap, the comparison with BOS and CHoCH, two 2021 cases and what 14 daily MSS on SPY and QQQ did next.
- Draw supply and demand zones
Supply and Demand Trading: Zones, Rules and Real Data
Base and departure rules, the four base patterns, how zones differ from order blocks and SMC, two SPY cases and a fixed test of 86 zone trades on SPY and QQQ.
- Read liquidity sweeps
Liquidity Sweep: How to Spot It and Trade the Reversal
Sweep or run, buy-side and sell-side liquidity, internal and external targets, SPY reversal, continuation and failed-reversal examples and a 25-year count of a fixed sweep rule.
- Spot bull and bear traps
Bull Trap vs Bear Trap: How to Spot a Trapped Market
What bull traps and bear traps are, the two signs of trapped traders, how to trade the reversal with a defined stop, and two real SPY examples from 2025.
- Learn the Turtle rules
Turtle Trading: The Original Rules of Richard Dennis
The key original Turtle trading rules: entries, position size with N, the 2N stop, adding units and the exits.
- Follow trends with rules
Trend Following Strategies: Rules, Tools and a 76-Year Test
How to recognize a trend, the main tools, seven common mistakes and what 224 trades of a 200-day filter on the S&P 500 since 1950 showed: 43 percent winners.